Questions and activities
Q1. Why is managing money wisely important for all individuals irrespective of their income?
Answer:
Managing money wisely is important for everyone because money is an important resource that must be used efficiently. It helps individuals balance their income and expenses, avoid unnecessary spending, save for future needs, and invest to achieve financial goals. It also helps people prepare for emergencies and maintain financial security, irrespective of their income.
Q2. How can budgeting help people balance their present needs with their future financial goals? Give examples.
Answer:
Budgeting helps people plan how to spend their income and how much to save for the future. It allows them to prioritise essential expenses and control unnecessary spending. For example, a family can plan its monthly expenses on food, rent, school fees, and transport while saving money for higher education or emergencies. In this way, budgeting helps people meet their present needs and achieve future financial goals.
Q3. School Reopening Budget Activity
Question: Your parents have given you ₹3,000 to prepare for the new school year. Make a list of the items you need, find out their prices (by visiting local stores, or asking a parent or teacher), and prepare a budget. Calculate the total cost and check whether it stays within ₹3,000.
- f your total is less than ₹3,000, you may add one additional item of your choice.
- If your total exceeds ₹3,000, decide which item(s) you can postpone or avoid buying to stay within your budget.
Use the budget template provided and ensure that all expenses are accurately calculated.
Answer:
| School Items | Amount (₹) |
|---|---|
| School bag | 600 |
| Books | 700 |
| Uniform and shoes | 800 |
| Notebooks | 300 |
| Pens | 100 |
| Pencils | 50 |
| Art supplies | 150 |
| Total Expenses | 2,700 |
| Savings | 300 |
| Total Amount | 3,000 |
Explanation: The total expenses are ₹2,700, which is within the budget of ₹3,000. Therefore, ₹300 remains as savings. This budget covers the necessary school items while keeping some money aside for future needs.
Q4. Why is saving alone often not enough to build wealth in the long run? How do investments help increase the value of money over time?
Answer:
Saving alone is often not enough to build wealth because money kept as cash may not grow in value, while inflation increases the prices of goods and services. Investments help increase the value of money by generating returns through interest, dividends, or an increase in asset prices. Compounding also allows returns to generate further returns over time. Therefore, investing helps people build wealth and protect the purchasing power of their money.
Q5. Investment Planning Activity
Question: Suppose you received cash gifts worth ₹3000 on your last birthday and decided to save ₹1500. With the help of your teacher, calculate the returns you might have earned if you had invested this amount in different combinations of investments. For example, what returns would you have received if you had invested ₹500 in a fixed deposit, ₹800 in the stock market, and ₹200 in gold? Try other combinations and find information on the returns from different investment options using reliable sources, such as newspapers, magazines, or official websites. Based on your findings, prepare an investment plan explaining why you think each investment option is suitable or unsuitable.
Answer:
| Investment Option | Amount Invested (₹) | Reason |
|---|---|---|
| Fixed Deposit (FD) | 500 | Offers assured returns and is suitable for people who prefer safety. |
| Stock Market | 500 | Shares have the potential to provide higher returns over the long term but involve higher risk. |
| Gold | 500 | Provides another option for investing savings. |
| Total Investment | 1,500 |
Explanation: I would divide my savings among different investment options instead of investing the entire amount in one place. Fixed deposits provide relatively safe and predictable returns, while stocks offer the possibility of higher returns with greater risk. The suitability of each investment depends on financial goals, risk tolerance, and the time for which the money can remain invested.
Note: Exact returns cannot be calculated without the applicable rates of return and the investment period.
Q6. How does inflation affect the value of money over time? Why should people consider inflation while making financial decisions?
Answer:
Inflation is the increase in the prices of goods and services over time. It reduces the purchasing power of money because the same amount of money buys fewer goods and services than before. For example, if a school bag costs ₹1,000 today and inflation is 6% per year, it may cost approximately ₹1,060 next year.
People should consider inflation while making financial decisions because savings that do not grow may lose purchasing power. Investing can help increase the value of money and protect it against the effects of inflation.
Q7. Different investment options involve different levels of risk and return. Do you think taking higher risks is always the best way to earn higher returns? How should a person decide which investment option is most suitable for them?
Answer:
No, taking higher risks is not always the best way to earn higher returns because higher-risk investments can also lead to greater losses. People should consider four important factors before investing: risk, return, time horizon, and liquidity.
They should choose investments according to their financial goals, the amount of risk they are willing to take, and when they may need the money. For example, fixed deposits are generally low-risk investments with steady but relatively lower returns, while shares have the potential for higher long-term returns but involve greater risk.
Q8. Why do people buy insurance policies even though they may never face a major loss? How does insurance provide financial security?
Answer:
People buy insurance policies to protect themselves and their families against unexpected events such as illness, accidents, loss of income, and property damage. Insurance works on the principle of risk sharing, in which many people pay premiums into a common pool.
When a covered loss occurs, the insurance company provides financial compensation according to the policy. Insurance reduces the financial burden of emergencies, protects savings, and helps families recover from financial setbacks. Thus, it provides financial security even if a major loss never occurs.
Q9. Imagine your family receives ₹1,00,000 from farming, a small business, livestock sales, and savings. Help your family decide how to use the money wisely.
Answer:
Step 1: Prepare a Budget
Question: Allocate the ₹1,00,000 among the following categories.
| Category | Amount (₹) | Percentage (%) |
|---|---|---|
| Savings | 20,000 | 20% |
| Education | 15,000 | 15% |
| Household expenses | 20,000 | 20% |
| Health and emergency fund | 10,000 | 10% |
| Farm or business investment | 20,000 | 20% |
| Home improvement | 5,000 | 5% |
| Festivals and recreation | 5,000 | 5% |
| Other | 5,000 | 5% |
| Total | 1,00,000 | 100% |
This budget gives priority to essential needs, savings, education, health, and productive investment while also allowing some money for recreation and other expenses.
Step 2: Needs vs Wants
Question: Classify each expense as a need or a want and give a reason.
Examples:
- School fees
- New mobile phone
- Better seeds or livestock feed
- Festival celebrations
- Water storage tank
Answer:
| Expense | Classification | Reason |
|---|---|---|
| School fees | Need | Education is essential for children’s learning. |
| New mobile phone | Want | It may be postponed if the existing phone meets essential needs. |
| Better seeds or livestock feed | Need | They help support farming and livestock activities. |
| Festival celebrations | Want | Spending can be adjusted according to the available budget. |
| Water storage tank | Need | It helps store water for household or farming requirements. |
Step 3: Save for the Future
Questions: Suppose your family saves ₹30,000 at 8% compound interest per year.
Using the formula = P(1 +\(r^)n\), where A: Amount, P: Principal, r: Rate of compound interest, n: number of years, calculate:
1. The amount after 5 years.
2. The interest earned.
Answer:
Given:
- Principal (P) = ₹30,000
- Rate (r) = 8% = 0.08
- Time (n) = 5 years
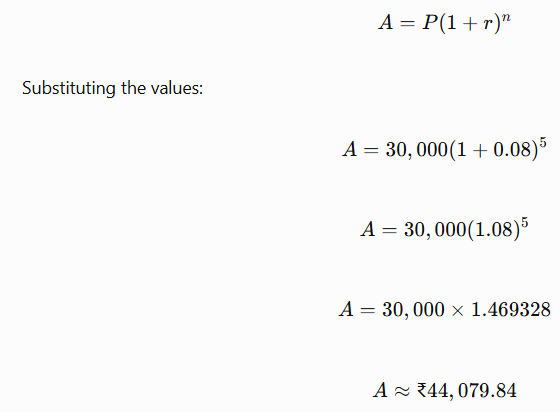
1. Amount after 5 years: ₹44,079.84
2. Interest earned:
Interest=A-P
=44,079.84-30,000
₹14,079.84
Therefore, the amount after five years will be approximately ₹44,079.84, and the interest earned will be ₹14,079.84.
Step 4: Save First, Spend Later
Question: Many financial experts recommend:
Expenses=Income-Savings
If your family receives ₹1,00,000 and saves ₹20,000 first, only ₹80,000 is available for spending. This helps ensure that future needs and emergencies can be met.
Answer:
Given:
- Total income = ₹1,00,000
- Savings = ₹20,000
Expenses=1,00,000-20,000
Expenses=₹80,000
The family has ₹80,000 available for expenses after saving ₹20,000. Saving first helps ensure that money is available for future needs and emergencies.
Step 5: Reflect
1. What percentage of the money did you save?
2. Which expenses were needs and which were wants?
3. How can savings improve a family’s financial security?
4. How does compound interest help money grow?
Challenge: Create a pie chart showing how the ₹1,00,000 was allocated across different categories
1. What percentage of the money did you save?
The family saved ₹20,000 out of ₹1,00,000.
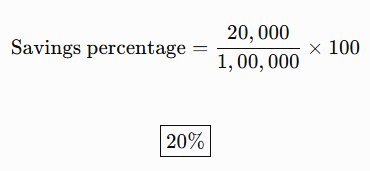
Therefore, the family saved 20% of its total income.
2. Which expenses were needs and which were wants?
Needs included education, household expenses, health and emergency funds, and farm or business investment. Wants included festivals and recreation. Some expenses, such as home improvement or buying a new mobile phone, depend on the family’s actual requirements.
3. How can savings improve a family’s financial security?
Savings help a family meet future needs and deal with unexpected expenses such as illness, accidents, or loss of income. They also provide money for future investments and reduce the need to borrow during emergencies.
4. How does compound interest help money grow?
Compound interest allows interest earned on an investment to generate additional interest over time. As a result, money grows faster over a longer period because returns are earned on both the original principal and the accumulated interest.
Challenge: Create a pie chart showing how the ₹1,00,000 was allocated across different categories.
The pie chart should represent the budget from Step 1, using the following percentages: savings 20%, education 15%, household expenses 20%, health and emergency fund 10%, farm or business investment 20%, home improvement 5%, festivals and recreation 5%, and other expenses 5%.
The Big Questions (Page no. 107)
Q1. What is personal finance and why is it important for individuals?
Answer:
Personal finance refers to the planning and management of an individual’s money to meet their needs and wants. It is important because it helps people decide how much to spend, save, and invest, and how to prepare for future financial needs.
Q2. What are the pillars of personal finance?
Answer:
The five pillars of personal finance are income, budgeting, saving, investing, and protection and risk management. These help individuals manage their money, plan expenses, build wealth, and protect their savings and assets.
Q3. What are some common savings and investment options?
Answer:
Some common savings and investment options are fixed deposits (FDs), Public Provident Fund (PPF), National Savings Certificate (NSC), Sukanya Samriddhi Yojana, bonds, stocks or shares, and mutual funds. These options help people save money and earn returns according to their financial goals and risk tolerance.
Q4. How can you protect your savings and assets?
Answer:
We can protect our savings and assets through insurance and responsible debt management. Health, life, and general insurance help protect individuals and families from financial losses caused by illness, accidents, death, or damage to property. We should also borrow money responsibly and repay loans on time.
Q5. What is income tax?
Answer:
Income tax is a direct tax paid on the income a person earns in a financial year. In India, the tax payable generally increases as income increases, following a progressive taxation system. The government uses tax revenue to provide public services such as schools, hospitals, roads, transport, and security.
Leave a Reply